
Editor-in-Chief Naomi Snyder is in charge of the editorial coverage at Bank Director. She oversees the magazine and the editorial team’s efforts on the Bank Director website, newsletter and special projects. She has more than two decades of experience in business journalism and spent 15 years as a newspaper reporter. She has a master’s degree in journalism from the University of Illinois and a bachelor’s degree from the University of Michigan.

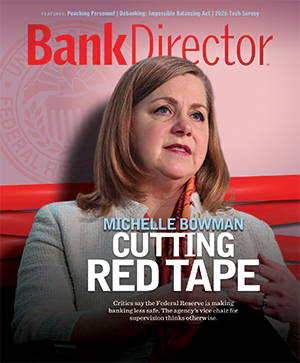
Miki Bowman: Cutting Red Tape
Critics say the Federal Reserve is hurting safety and soundness. The agency’s vice chair for supervision thinks otherwise.
Close
About the authors
Written by
Naomi Snyder
Editor-in-Chief
Naomi Snyder
Editor-in-Chief
*This article was published in Bank Director magazine’s fourth quarter 2026 issue. For information on subscribing, click here.
Michelle “Miki” Bowman’s background doesn’t make her look like the sort who would normally lead the Federal Reserve’s supervision and regulation function. She doesn’t have a degree in economics or Wall Street employment history. She got a degree in advertising and journalism from the University of Kansas and a law degree from Washburn University, also in Kansas. Her experience in banking was working as a compliance officer inside a community bank owned by her family in Council Grove, Kansas, a town that has about 1,000 households.
But in 2015, Congress set aside a Federal Reserve governorship for someone with a community banking background. And she had other qualifications for the role. She was no stranger to bank regulation and was serving as the State Bank Commissioner of Kansas at the time. She had also worked in Washington as a congressional aide, where she helped put together the Department of Homeland Security as a deputy assistant secretary and policy adviser to Homeland Security Secretary Tom Ridge.
She is now one of the longest tenured Fed governors on the board. In addition to serving on the Federal Open Market Committee setting interest rates, she was appointed by President Donald Trump in 2025 as vice chair for supervision, meaning she’s one of the most powerful women in banking. “She’s been a great advocate for the community banks,” says Heath Tarbert, a former chairman and CEO of the Commodity Futures Trading Commission. “While she started off as being a critically important voice and perspective for community banks, now she is one of the foremost experts and leaders in financial regulation, and I would say economic policy more generally.”
Her friends describe the 55-year-old as a warm, genuine person, almost a novelty in hyper-competitive Washington. A Midwesterner with good listening skills and intellectual curiosity, her policies have tailored regulations to ease burdens on smaller banks and focus on financial risks. Critics say she and other Trump administration regulators are rolling back rules in a way that will hurt the safety and soundness of the banking system. That’s not the way she sees it. “We’re trying to rightsize regulations that went too far,” she says. “One thing that we recognize with the introduction of the Dodd Frank-era regulations, a lot of those requirements were over-calibrated.”
Make Community Banking Great Again
A visit to the Federal Reserve Board of Governors building requires going through three layers of security. After running that gauntlet, a staff member will escort you to the fifth floor, where Bowman’s office sits behind a wall of Fed chairmen portraits throughout history. Her space evokes tradition, with its dark wooden, antique-style desk on slender legs. A red ball cap on a shelf is emblazoned with the phrase: Make Community Banking Great Again. Dressed in a navy colored dress, she shows off a photo of her family’s bank, Farmers and Drovers Bank, founded in 1882.
Despite her ties to tradition, she’s also shown an interest in modernization and innovation. The chairman of the U.S. Securities and Exchange Commission, Paul Atkins, serves with her on the international Financial Stability Board, where he says she brings a clear-eyed view toward updating antiquated processes. “And I’ve seen her at social situations, too, where she is a wonderful hostess, and her staff really likes her.”
She surrounded herself with policy staff who supported her vision, some of whom came from outside the Fed but were inspired by her perspective outlined in speeches she had been giving for years. She prefers to go to that staff to help implement a vision, asking them to come up with ideas so everyone feels they have a voice. She characterizes her approach as different from some predecessors. “They’re used to a policymaker coming in and saying, ‘I want this, write this,’” she says.
Bowman has a reputation in Washington as a straight talker. “She doesn’t stand on pretense and is very approachable,” Atkins says. Randal Quarles, who served as Fed vice chair of supervision during Trump’s first term, agrees. He remembers she was one of the easiest people to talk to in Washington. “She didn’t have a ‘side,’ as my grandfather would say,” he says.
Rodney Hood, who was chairman of the National Credit Union Administration and acting comptroller of the currency before Jonathan Gould was confirmed, remembers Bowman invited him over to dinner with her family one evening. This isn’t standard practice in Washington, he says, where the joke is that if you want a friend in Washington, get a dog.
She also has an independent streak. “She would think carefully, come to a view,” says Quarles, now executive chairman and cofounder of the investment firm The Cynosure Group. “And then you weren’t going to peer pressure Miki off a view that she felt solidly about. You could have a very useful discussion with her about it, but it wasn’t going to be, ‘OK, I’ll go along because it’s uncomfortable being alone on this issue.’ I don’t think that ever bothered her.”
In 2024, on a half-point rate cut decision, she became the first governor since 2005 to vote against the rest of the FOMC, advocating instead for a smaller, quarter-point cut. It wasn’t viewed by everyone as independent. She was aligned with presidential candidate Trump at the time, who had publicly advocated against a cut that could have helped the Democratic presidential candidate, Kamala Harris.
Bowman also is unique in that she may be one of the more popular regulators for community bankers in a long time. First and foremost, being a former community banker instead of a Wall Street banker or big bank lawyer made her stand out among D.C. heavyweights. “The conversation is simply different with Michelle Bowman,” says Doug Wareham, the CEO of the Kansas Bankers Association. She frequently accepts invites to listen to bankers, he notes, “because Miki is a banker at heart, and that is where she starts from all of those conversations — her own experience.”
During Covid-19, Bowman called about 220 bankers to get updates on the Paycheck Protection Program and their struggles. “During Covid, what I realized is that we’re very isolated here,” she says. “You cannot do this job unless you are talking with people who are in the real economy.” She has continued her outreach today. “Thousands of bankers I’ve met across the country,” she says. “And I always ask them, ‘If we could fix something, what would it be?’”
Chris Furlow, the CEO of the Texas Bankers Association, says her background as a community banker, a state regulator and a federal regulator brings balance to her perspective, a balance he feels was lacking under the Biden administration. “Having been an actual community banker, Miki understands from a risk perspective what works and what doesn’t,” he says. “I think the biggest impact is that bankers don’t feel like they are guilty until proven innocent.”
Furlow once invited Bowman to speak to his association. For a prop, he piled 800-page stacks of paper regulations wrapped in red tape on the stage, regulations he says were issued by the Biden administration in the year 2023 alone. “People who would criticize what they would call ‘regulatory rollbacks’ don’t realize just how far the previous administration’s regulators had gone,” he says.
Less Capital
So far, her policy positions have mostly aligned with the preferences of community banks, but her supporters see the moves as sensible adjustments, not a chainsaw-like approach. Under her watch, the Fed and other federal regulators jointly reduced the required community bank leverage ratio, a measurement of capital adequacy, from 9% to 8%. She and other regulators also removed references to “reputation risk” from many interagency documents, saying examiners would refocus on material financial risks — in line with an August 2025 executive order from President Donald Trump.
Bowman also sits on the Federal Financial Institutions Examination Council, which focuses on codifying exam procedures across agencies. It’s probably one of the less exciting bodies in D.C., but the council’s exam manuals are important to the daily lives of community banks. Through the council, Bowman decided to improve training for examiners and reworked the CAMELS framework, the exam scoring system for banks where regulators review capital adequacy, asset quality, management, earnings, liquidity and sensitivity to market risk. The proposed changes would remove special consideration given to the “management” rating under the theory that heightening that factor in the exam might de-emphasize the importance of financial risks. Among changes, the proposal removes assessments related to “management depth and succession” and “responsiveness to recommendations from auditors and supervisory authorities.”
There are few policy details that don’t interest her. Hal Scott, a former Harvard Law School professor and president of the nonprofit Committee on Capital Markets Regulation, says Bowman has been looking into the importance of the Fed’s role in supporting liquidity in the system. He argues that the Fed didn’t provide liquidity to three large, regional banks that failed in 2023, despite having a remit to do so. He’s also been supportive of her and the other federal regulators’ revamping proposed capital rules in March 2026 to comply with the international Basel accords. That includes a provision expected to reduce common equity Tier 1 capital requirements by 7.8% for banks below $100 billion in assets.
Europeans had been calling for higher capital standards as a bulwark against losses in the wake of the 2007-09 financial crisis, which hurt economies across both continents. Bowman and others in the Trump administration concluded that American banks already are better capitalized than they were during the financial crisis, and across-the-board higher levels of capital would lead to less lending and economic growth. Hood flew to Basel, Switzerland, in 2025 with Bowman and the American delegation. “With [banks] all hovering over nearly 12% Tier 1 capital,” he says, “to have put any more requirements on them over that would’ve just had capital waiting on the sidelines, as opposed to being used for banks to grow, to invest and to stimulate the economy.”
Bowman says the capital proposal, which also addresses risk weights for mortgages, will encourage banks to re-enter a mortgage business where they scaled back after the passage of the Dodd-Frank Act. “We have seen a great deal of consumer activity move into fintechs that have much less regulation and oversight,” she says.
The prior vice chair of supervision under Biden, current Fed governor Michael Barr, had proposed higher levels of capital that never went into effect. “Bank capital rules help to ensure that banks fund themselves with capital commensurate with the risks of their activities and the risks that they pose to the U.S. financial system,” Barr said in March 2026 in response to the Trump administration proposal. He pointed out that steep reductions for banks with up to $100 billion in assets help institutions that are far larger than community banks — banks that are some of the largest in the country and do pose risks. “These significant reductions in capital requirements are unnecessary and unwise,” he said.
Mark Williams is a master lecturer of finance at Boston University. He says reducing capital requirements runs contrary to Bowman’s job of enhancing the safety and soundness of the banking system. “It is ironic that the most senior person at the Fed responsible for ensuring bank safety and soundness is also the one advocating hardest for reducing standards,” Williams wrote in an email.
Her supporters disagree with that assessment. “Some of this is simply a recalibration,” Tarbert says. “I think Vice Chairman Bowman continues to believe in robust standards. Where she has, I think, made an important point is that many of these international standards were created for large, complex, cross-border institutions with trillions of dollars in assets — not the typical American community bank.”
Innovation or Threat?
Meanwhile, Bowman is also working to improve exam communication between federal and state regulators, who are the primary supervisors for more than 3,400 state-chartered banks. “I don’t think anybody in one of these agencies has ever told [state regulators] directly, ‘We have to engage with you. We care about what you think. You own the charter of this institution,’” she says.
Improved communication with state supervisors can help avoid conflicting exam reports from different supervisors. Banks are supervised by multiple entities, for example, the state and the Federal Deposit Insurance Corp. or the state, the Fed and the FDIC. “If we say they’re a 3-rated bank for a particular area, and the state says they’re a 2, what are banks supposed to do with that?” she says.
While community banks applaud some of the moves to remove regulatory burdens, not all of them are as keen on the administration’s push to help the crypto industry. Bank lobbying groups have argued for laws that would ban crypto firms from paying what looks like yield, out of fear that such instruments would drain deposits from banks. That, in turn, would reduce lending nationwide, the argument goes, since crypto can’t be used to lend.
The Federal Reserve has proposed nonbanks such as crypto firms could be granted “skinny” master account access to the Fed’s payment rails, a privilege normally reserved for regulated banks. Bowman has exhibited an openness to blockchain and cryptocurrencies, equating them with the kinds of innovation she has always supported, but has remained neutral on some of the details. She brings up the fact that when she was a compliance officer, she had pushed her family bank to offer mobile banking and e-statements when it was slow to follow the trends.
Referring to the crypto bill known as the Clarity Act, which had not passed as of press time, Bowman says she doesn’t have a view on how that should be structured but looks forward to implementing the laws in a way that limits risks. “I have a supervisor’s view that we need innovation in the banking system,” she says. “I think it’s important that banks are able to innovate.”
Tarbert now works as president of the stablecoin issuer Circle. He says Bowman thinks of crypto correctly as something that shouldn’t operate outside the banking system. He says the regulatory view in the administration is an openness to blockchain’s promise to improve the financial system, which is a change from the prior administration. It’s more about, “Let’s think carefully about how banks are utilizing and can utilize these products, and let’s regulate and supervise accordingly,” he says. “I do think it’s a shift.”
Williams at Boston University says Bowman’s position is similar to Trump’s in believing that crypto is synonymous with innovation. But criminal enterprises are big users of crypto, benefitting from the technology’s inherent anonymity, he says. Cryptocurrencies also aren’t FDIC insured, so they’re more subject to flight and can have a destabilizing effect on the banking industry. Signature Bank, which failed in 2023, had 22% of its uninsured deposits tied to digital assets, including crypto firms, according to a FDIC post-mortem report. “For the chief regulator to say reputational risk is not important anymore in the examination process,” he says, “and then on top of it say, ‘Hey, maybe you as bankers should try crypto. You’ll like it.’ It’s mind-boggling.”
Another point of contention is Bowman’s move to cut 30% of the Federal Reserve Board’s supervision and regulation staff. Bowman says this was policy staff at the Fed board, not the supervisory network of examiners throughout the country that are assigned to the Fed regional banks. She says her goal was to get down to about 350 to 360 policy people from about 500, through buyouts rather than layoffs, and that the staff had doubled after the financial crisis. “But the way that we grew didn’t make sense,” she says. “It created silos, and it had four different risk apparatuses that weren’t talking to each other or effectively informing the work that we were doing.”
The Path to Washington
Bowman didn’t set out to become one of the most powerful women in banking, but her interest in governance started at a young age. She was president of her senior high school class in 1989 and voted “most likely to succeed.” She came to D.C. in 1995 to work as an intern for Kansas Sen. Bob Dole. She took classes at night at nearby American University, finishing up her law degree at Washburn. She was aware someone from Kansas would have to work harder to prove herself. For example, Bowman took the New York bar rather than the Kansas bar to pass the tougher test.
She served on congressional committees such as the transportation committee, working on emergency management issues that included the interoperability of equipment and radios. When 9/11 happened, she was charged with taking a congressional delegation to New York when the fires were still smoldering. Just as she had feared, the radio systems of emergency responders had not worked well. Congress responded to the disaster by creating the Department of Homeland Security. As one of its first employees, she led merger efforts among 22 agencies and departments. Not everyone was happy to see their job or role change. “It helps you figure out how to recognize and listen,” she says. “It doesn’t mend fences, but it helps bring people together when you know you have to work together at the end.”
Kathy Kraninger was working at Homeland Security as well and met her during this time. Kraninger would later become the head of the Consumer Financial Protection Bureau during the first Trump administration and says Bowman was honing her skills at building trust and coalitions. “Both of us care about lasting impact and lasting change,” Kraninger says. “To do that, you need people to actually believe in what it is that you’re trying to institute to have really a lasting impact. And that is something that she was really good at.”
Bowman’s job also involved shepherding dozens of different appointees of the new department through congressional confirmation hearings. The days were long, seven days per week. After about a decade in Washington, she was getting burned out. The neighborhood where she lived was rougher than it is now, near 14th and S streets. She worried about whether she had packed the emergency “go” bags that Homeland Security was urging people to prepare in the wake of the attack.
Meanwhile, her husband worked as a consultant at McKinsey & Co. and eventually he got an opportunity to move them to London. In 2004, “it was time for us to leave Washington,” she says.
In London, she and her husband had two children, a boy and a girl, and she started her own consulting firm working with clients in the European Union and United Kingdom. She was pleased for the chance to go out on her own, but she wanted her children to get to know their grandparents. Her father, who worked at the privately owned family bank, which now has $224 million in assets, was ill.
After five years in London, the couple moved back to Council Grove. Bowman started at Farmers and Drovers as a vice president but rotated through a variety of jobs as a teller, in the back office and in compliance. People tried to tell her not to go into compliance: It was a dead-end job, after all. The way Bowman tells it, she wasn’t secretly hoping to go back to Washington. She really thought she would stay in her family’s bank.
Bowman was president of the local chamber of commerce. She joined Leadership Kansas, a statewide group for educating leaders, and she became president of the Rotary Club — all the things community bankers do. Soon, she met a woman named Kim Borchers as part of a leadership group for Republican women in Kansas. Borchers, who now owns Bird Dog Recruitment and Consulting, was working for Kansas Gov. Sam Brownback and was impressed by Bowman. She asked Bowman if she was interested in the Kansas banking commissioner job, which had recently opened but was normally a sort of “swan song” for retiring bankers. Bowman took the position in Topeka, about a 60-mile commute from her home.
Bowman was the first woman to hold the title, Borchers says. She was also the youngest person with the job, and she began holding roundtables with bankers throughout the state to get their feedback on regulations. She worked to reorganize and modernize a department that hadn’t changed in 40 years, says Kansas Bankers Association’s Wareham. “You can’t do that without ruffling some feathers, because change is hard,” he says. “But she’s not somebody who’s going to shy away from leadership and trying to make things more efficient and effective.”
In less than two years, she had joined the Federal Reserve Board of Governors for the community bank position. For Kraninger, who is now CEO of the Florida Bankers Association, the impact Bowman has had isn’t about any one single regulatory change.
“It really is the philosophy and totality of these actions that make a huge difference,” she says. “And the attitude of the regulators now to get to the place that is smart, to get to the place that is focused on safety and soundness. And absolutely, Vice Chair Bowman has that in spades. That is absolutely helping community banks in Florida in a big way.”
Quarles agrees. “It would be hard to find someone who has a broader set of experiences around what makes a safe bank regulatory system but also what makes an efficient bank regulatory system,” he says.
WRITTEN BY
Naomi Snyder
Editor-in-Chief
Editor-in-Chief Naomi Snyder is in charge of the editorial coverage at Bank Director. She oversees the magazine and the editorial team’s efforts on the Bank Director website, newsletter and special projects. She has more than two decades of experience in business journalism and spent 15 years as a newspaper reporter. She has a master’s degree in journalism from the University of Illinois and a bachelor’s degree from the University of Michigan.