
Polo Rocha is a contributing writer for Bank Director.
‘Tremendous’ Electric Demand Prompts Surge in Bank Solar Financing
Despite policy headwinds, banks that have focused on solar and renewable energy financing say the market remains hot.
Close
About the authors
Written by
Polo Rocha
Contributing Writer
Polo Rocha
Contributing Writer
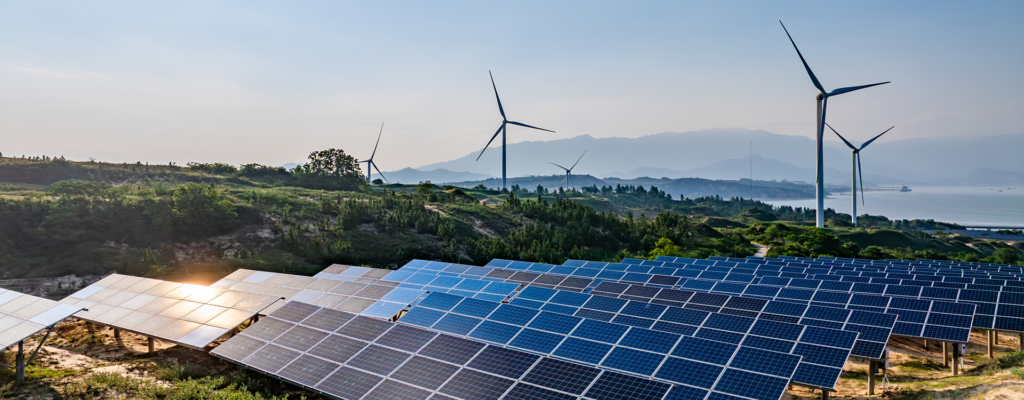
Far from stalling out, renewable energy is powering loans at banks that lend to the sector, whose growth is helping fulfill U.S. electric needs even as federal support eases.
Renewables faced uncertainty last year, as Congress curtailed tax credits that helped the industry boom after the pandemic. But one thing today is certain: The country needs more electricity.
Whether it’s because of data centers or plugged-in devices, more solar farms and renewable projects are popping up — plus loans to finance their construction and long-term operation.
“We’re in ‘make hay while the sun shines’ mode,” says Jennifer Williams, managing director for renewable energy lending at Live Oak Bancshares, a $16 billion asset bank in Wilmington, North Carolina. “Everyone is incredibly busy.”
It is shining brightly for solar, which recently overtook coal in monthly U.S. electricity generation for the first time ever, according to the think tank Ember. Wind is seeing less momentum but is growing, nonetheless. Investments are jumping in the battery and storage sector, which stows away energy when the sun isn’t shining or wind isn’t blowing — and which will continue to benefit from tax credits.
Tax credits for solar and wind developments will be phased out in the next few years, dampening medium-term growth projections. But there’s little sign of demand tapering yet.
U.S. renewables investment surged 54% in the first half of 2026 compared to a year earlier, BloombergNEF says, partly because of “unprecedented load growth from data centers.”
There is “tremendous demand right now in the U.S. for power,” says Frank J. Conley, managing director for renewable energy finance at $129 billion asset Pinnacle Financial Partners in Atlanta, Georgia. Solar is “the quickest, most efficient way to put those electrons into the grid,” he says, and developers are having a hard time keeping up.
“I know there’s some changes going on, but it’s been a fantastic few years in the space,” Conley says.
Commercial Boom Continues
Bank lending to renewables varies in size and style. It includes loans to homeowners for solar panels, where federal tax credits faced a fast expiration under the One Big Beautiful Bill Act.
Loans to developers of renewables projects — whether community solar projects or massive utility-style projects — are where banks are seeing significant growth. Activity boomed ahead of a July 4 deadline for solar and wind projects, which got grandfathered into tax credits for the next few years, as long as they’d started construction.
The consumer solar world has retreated a ton, but everything else is kind of exploding, says Lex Ford, CEO of $1.8 billion Climate First Bank in St. Petersburg, Florida. Ford says he’s “surprised more banks aren’t involved” in the commercial business, since it includes firm commitments from utilities to buy power from renewable developers. “There’s a lot of opportunity and demand that I don’t think us, or any bank that’s in it, can wholly handle,” he says.
A New Entrant
One relatively recent entrant: $87.7 billion-asset Flagstar Bank in Hicksville, New York. It’s part of the bank’s journey to grow commercial loans under an overhaul led by Executive Chairman and CEO Joseph Otting, the former Comptroller of the Currency. “A lot of our clients are telling us they’ve never been busier,” says Jerry Wells, who was hired last year to lead Flagstar’s power and renewables business.
Developers felt some angst about tax credits last year, but once their future was clear, developers quickly became “absolutely inundated with requests for new projects,” he says. The bank has focused on utility-scale projects, Wells says, partly because the due diligence needed is less time-consuming when working on a few large projects and not dozens. “We’re very relationship-oriented, doing repeat transactions,” he says. “We’re continuing to grow our book. I think it’s a great time to be in the renewable industry.”
Financing Community Solar
Rather than working on utility projects, South Bend, Indiana-based 1st Source Corp., lends to smaller-scale and community solar projects. Those tend to be built, approved and plugged into electric grids quicker, says Ryan Fenstermaker, who heads the $9.3 billion asset bank’s solar financing division. “That tends to be a better fit for us,” he says. “We can add value there, and they fit into the right size parameters.”
The bank started lending to solar projects a decade ago, building on its tax credit expertise to finance projects for municipalities, smaller utilities, schools and universities. Nowadays, it’s adapted alongside the growing industry by working more often with independent power producers — who develop solar projects that plug into energy grids. “I feel like we’ve picked a good lane,” Fenstermaker says.
State-level incentives in Illinois, Massachusetts and elsewhere are driving activity in some markets. So, too, is the need to replace energy from the legacy coal plants being retired after decades in operation. One massive driver, however, is the “electrification of everything,” from electric cars to residential heating. Meeting that demand while keeping costs low is the challenge the industry is trying to meet.
“At the end of the day, all stakeholders throughout the industry want to deliver reliable, affordable energy to all of us,” Fenstermaker says. “We all want to be able to go turn our lights on, turn the AC on at home for as affordable as possible — and know that it’s going to work.”
Tax Credits as an Alternative
Other banks aren’t lending to the industry directly, but they are investing in the tax credits that make those deals possible. The economics of doing so are “very, very compelling” and lower banks’ tax burden, says Josh Miller, CEO of KeyState, which offers a platform for banks to invest in battery storage and solar tax credits.
The platform recently hit $1 billion in investments from community banks, leading to some $125 million in federal tax benefits. But only a small chunk of banks participates in the market, he says. “They’re just leaving money on the table every year, and this is a federal tax incentive that is available to them,” he says. “They’re always looking for ways to level the playing field with the large national banks and with the credit unions, and this is low-hanging fruit.”
As with any investment, tax credit deals are never risk-free — errors can disqualify a deal from tax benefits. But risks can be mitigated with proper underwriting and due diligence, as well as working with tax advisers, deal lawyers, appraisers and engineers, he says, which KeyState does for banks investing in the credits.
Focusing on Credit Quality
Banks that lend to the sector say they’re also staying vigilant amid the flurry of activity. A decade of experience is helping Indiana-based 1st Source Bank, Fenstermaker says, by better informing any financial models and stress testing of projections. “There’s always going to be surprises, but the more you can use data and the information that you have from historical performance to guide future performance, that’s useful for both the clients and for the bank,” he says.
With so much activity across the industry, there’s an even bigger emphasis on quality, says Live Oak’s Williams. “A clear, straightforward project with focus and a good deal team is going to rise to the top much more quickly,” Williams says.
That means lending to projects with sponsors who are committed to the market over the long term, have strong liquidity, work with experienced contractors and use top-tier equipment. “When you have a lot of opportunities cross your plate, trust and transparency and repeat partnerships matter more than ever,” she says.
WRITTEN BY
Polo Rocha
Contributing Writer
Polo Rocha is a contributing writer for Bank Director.