
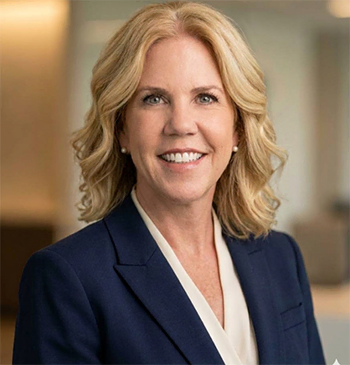
Deborah Sweeney is a lawyer turned entrepreneur who runs a number of divisions under Deluxe, to which she sold her company, MyCorporation.

Why Banks Must Shift From Compliance to Forward-Looking Strategy
Here’s how bank boards can shift their work from reviewing paperwork to preparing their banks for changes in the environment.
Brought to you by Deluxe

Close
About the authors
Written by
Deborah Sweeney
VP Online Acquisitions
Deborah Sweeney
VP Online Acquisitions
If recent economic headlines proved anything, it is how quickly comfortable assumptions dissolve. The surprise contraction in July nonfarm payrolls, dropping 23,000 jobs alongside sharp downward revisions, sent treasury yields tumbling and reset rate predictions in an instant. Right as 2nd quarter earnings wrapped, community bank executives were left wrestling with the same headache: stubborn funding costs and squeezed net interest margins (NIM).
Most leadership teams respond to this volatility by looking backward. They analyze last quarter’s call reports, dissect cost of funds creep and build thicker board decks. But that is a mistake.
There are striking parallels between standard corporate leadership and running a community bank. At their core, both are operating businesses. Winning requires an entrepreneurial edge: identifying market opportunities, deeply understanding your constituents and relentlessly leveraging data to expand margins.
Yet too many bank leaders treat their institutions as regulated balance sheets rather than dynamic businesses. They spend 80% of their time reporting on what already happened instead of positioning for what comes next.
Here is how to break that habit and build a forward-looking organization.
1. Measure Forward, Not Backward
NIM is still your primary lever, but trailing calculations are practically useless when interest rates move this fast. If your chief financial officer is only bringing historical averages to the table, you are driving by looking in the rearview mirror.
Effective teams run dynamic, scenario-based margin models. Stress your balance sheet for both extremes, such as a sharp economic cooldown on one side or prolonged deposit stickiness on the other.
Crucially, policy is a balance sheet risk. Take the Senate delaying its vote on the Clarity Act until September after heavy industry pushback. If yield-bearing stablecoins gain legal ground without safeguards, low-cost community deposits will bleed into crypto. Forward-looking boards must model those runoff scenarios today and translate those findings into simple board dashboards. If yields drop or deposit flight accelerates, which funding levers kick in?
2. Reclaim the Boardroom
Most bank board meetings are structured for compliance, not strategy. Directors wade through hundreds of pages of historical reports, nod along to committee updates and save fifteen minutes at the end for strategic discussion.
Flip this ratio. Adopt a consent agenda to handle routine financial, committee and compliance reporting in a single vote, requiring directors to review the materials in advance. Clearing 80 to 90 pages of backward-looking documentation off the docket instantly frees up more than 75% of your board meeting for forward-looking strategy. Fiduciary duty requires deliberate oversight, not passive consumption of old news. Dedicate that reclaimed time to forward scenarios and clear decision triggers: If X happens to our deposit costs, we execute Y pricing shift. Moving from “here is what happened” to “here is what we will do next” turns your board into a true competitive advantage.
3. Legal Documentation Is Your Operational Shield
As a former law professor and partner, I view legal governance as an offensive tool, not administrative bloat. Documenting the logic, risk tolerances and economic assumptions behind your pricing and hedging choices establishes that the board exercised informed business judgment.
This legal foresight applies directly to structural shifts in the industry. For example, the Federal Deposit Insurance Corp. announced a new two–phase de novo bank deposit application process offering contingent authorization within 120 days under the 21st Century ROAD to Housing Act. Whether new de novo charters represent local competitors or future acquisition targets, faster market entry changes deposit pricing and deal valuations. When M&A opportunities arise, clean governance records, well-audited vendor contracts and bulletproof modeling directly increases deal certainty and protects against post-closing indemnity disputes.
Four Concrete Steps for the Coming Quarter:
- 1. Institute a consent agenda. Package historical financial and compliance reports into a single vote to free up 75% or more of board meetings for forward strategy.
- 2. Replace the 100-page board deck. Transition to a concise dashboard, tracking NIM, liquidity and capital under three distinct rate scenarios.
- 3. Set operational trigger points. Define precise metrics that automatically prompt rate adjustments or balance sheet rebalancing.
- 4. Treat M&A and regulatory shifts as core disciplines. Align your balance sheet models with regulatory representations long before entering deal talks or facing new local entrants.
Community banking will always be built on local relationships. But relationships alone won’t protect your margin when macroeconomic and legislative tides turn. By thinking more like an agile operating executive, documenting your legal rationale and focusing relentlessly on forward strategy, you can protect profitability today while holding the cards for tomorrow.
WRITTEN BY
Deborah Sweeney
VP Online Acquisitions
Deborah Sweeney is a lawyer turned entrepreneur who runs a number of divisions under Deluxe, to which she sold her company, MyCorporation.